Data as-of 30 Oct 2026 · Last rebuild 3 Nov 2026, 7:25 AM HKT · Next: Invesco holdings often lag ~1 business day · rebuild weekdays · holdings as of 30 Oct · 2 business days
Bank Additional Tier 1 (AT1) bonds monitor (1 business day lag · as of 30 Oct 2026)
Plain English: AT1 / CoCo bonds are bank Additional Tier 1 capital that can be written down or converted in stress; YTC is yield assuming the issuer calls at the next call date; Z-spread is extra yield over Treasuries (bp); call is that next optional redemption date. Universe: Invesco AT1D / iBoxx AT1 ETF holdings.
Universe: constituents of Invesco USD AT1 CoCo Bond UCITS ETF Dist (AT1D, ISIN IE00BG0TQB18) — 100% proxy of iBoxx USD Contingent Convertible Liquid Developed Market AT1 (8% Issuer Cap) Index — 104 bonds (95 with weight > 0; 99 with ISIN). Holdings as of 30 Oct 2026 from the Invesco daily holdings export (Market Price → PX from ETF; page NAV as of 2026-10-30).
Bold solid = indexed total return (left axis): AT1D SW, S&P 500 TR (^SP500TR), and 5yr UST TR (Yahoo IEI / FRED proxy), all rebased to 100. Blue dotted = AT1DW SW daily market price (Yahoo AT1D.SW close, not TR / not indexed) on the right axis.
Bold solid = indexed total return (left axis): AT1D SW, S&P 500 TR (^SP500TR), and 5yr UST TR (Yahoo IEI / FRED proxy), all rebased to 100. Blue dotted = AT1DW SW daily market price (Yahoo AT1D.SW close, not TR / not indexed) on the right axis.
5Y sovereign CDS mid spreads (bp, left axis): UK, France, Switzerland, Netherlands, Spain, Japan from World Government Bonds (public, no login). Weekly samples. Purple dotted = 5yr UST yld (FRED DGS5 running yield %) on the right axis.
5Y sovereign CDS mid spreads (bp, left axis): UK, France, Switzerland, Netherlands, Spain, Japan from World Government Bonds (public, no login). Weekly samples. ~1-year window. Purple dotted = 5yr UST yld (FRED DGS5 running yield %) on the right axis.
- Zero-weight Credit Suisse AT1s (written down / skipped coupon) and curated non-call events are listed in the Defaulted / skipped coupon / non-called box below the main list — CS write-downs are not in the table.
- BBG ticker = Bloomberg Corp issuer root only (e.g. BACR, SOCGEN, SANTAN) — coupon / V… / PERP / RegS omitted (already in Cpn / Name). Full OpenFIGI string + equity issuer code on hover.
- Bond marks: PX from ETF is the Invesco daily holdings Market Price. Coupon from that file when present; rating / issue size / call from factsheet enrichment; YTC uses the ETF mark. Countries ordered by total issue size outstanding; within each country, bonds sorted by Call ascending (nearest first; blank Call at bottom).
- Click any column header to flat-sort (↑ then ↓); a third click — or the toolbar Restore original button — returns to country → Call order.
- Default view hides YTC < 7% (blank YTC stays visible) — check Show YTC < 7% next to Restore original to reveal them.
- Reset highlight: light green = Top 10 highest Reset; pink = Lowest 10 Reset (full universe; same colours on main table, Top movers, and Top/Lowest Z-spread boxes; stays after YTC / search filters).
- Methodology: append
?m=0to hide the footer.
Top 15 names by ~5-day % change in average mark (Invesco ETF holding price). Shows signed moves (+gain / −loss); ranked by |%| so both up and down movers appear — not daily points. Window: 2026-10-23 → 2026-10-30 (7d).
| IG/HY | # | BBG ticker | Name | Country | Cpn | PX | Z-S | YTC | Call | Reset | Rating | ISIN | Prior (−5D) | Latest | Δ | ~5d % |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| HY | 1 | SOCGEN | Societe Generale SA | France | 8% | 95.88 | 408bp | 8.85% | 2033-03-29 | 3.10% | BB/Ba2/BB | USF8500EAA94 | 93.95 | 95.88 | +1.93 | +2.05% |
| HY | 2 | SOCGEN | Societe Generale SA | France | 8.5% | 101.01 | 352bp | 8.32% | 2034-03-24 | 4.15% | BB/Ba2/BB+ | USF8500RAD47 | 99.08 | 101.01 | +1.93 | +1.95% |
| IG | 3 | BNP | BNP Paribas SA | France | 4.625% | 86.94 | 368bp | 8.15% | 2031-02-25 | 3.34% | BBB-/Ba1/BBB- | USF1R15XL357 | 85.30 | 86.94 | +1.64 | +1.93% |
| IG | 4 | LLOYDS | Lloyds banks | UK | 6.625% | 94.80 | 257bp | 7.42% | 2035-09-26 | 2.68% | Baa3/BBB | US539439BF59 | 93.07 | 94.80 | +1.73 | +1.86% |
| IG | 5 | BNP | BNP Paribas SA | France | 8% | 100.33 | 344bp | 7.92% | 2031-08-21 | 3.73% | BBB-/Ba1/BBB | USF1067PAF39 | 98.81 | 100.33 | +1.52 | +1.54% |
| IG | 6 | BNP | BNP Paribas SA | France | 7.2% | 91.63 | 354bp | 8.50% | 2036-04-16 | 2.94% | BBB-/Ba1/BBB | USF1067PAK24 | 90.24 | 91.63 | +1.38 | +1.53% |
| HY | 7 | SOCGEN | Societe Generale SA | France | 7.125% | 89.95 | 408bp | 8.76% | 2035-07-14 | 2.95% | BB/Ba2/BB+ | USF8500RAF94 | 88.68 | 89.95 | +1.27 | +1.43% |
| HY | 8 | SOCGEN | Societe Generale SA | France | 5.375% | 90.57 | 400bp | 7.91% | 2030-11-17 | 4.51% | BB/Ba2/BB+ | USF8500RAA08 | 89.31 | 90.57 | +1.26 | +1.41% |
| IG | 9 | INTNED | ING Groep NV | Netherlands | 7.25% | 99.46 | 285bp | 7.34% | 2034-11-15 | 4.08% | BBB-/Ba1/BBB | XS2885225966 | 98.09 | 99.46 | +1.37 | +1.40% |
| IG | 10 | ACAFP | Credit Agricole SA | France | 6.7% | 92.03 | 326bp | 8.06% | 2034-09-22 | 3.60% | BBB-/BBB | USF2280BAA47 | 90.80 | 92.03 | +1.23 | +1.36% |
| IG | 11 | BNP | BNP Paribas SA | France | 4.5% | 89.02 | 383bp | 8.17% | 2030-02-24 | 2.94% | BBB-/Ba1/BBB | USF1R15XL274 | 87.84 | 89.02 | +1.18 | +1.34% |
| IG | 12 | BNP | BNP Paribas SA | France | 7.45% | 94.94 | 363bp | 8.26% | 2035-06-26 | 3.13% | BBB-/Ba1/BBB | USF1067PAH94 | 93.70 | 94.94 | +1.24 | +1.32% |
| IG | 13 | NDAFH | Nordea Bank Abp | Finland | 6.75% | 96.17 | 305bp | 7.42% | 2033-11-09 | 2.72% | BBB/BBB+ | USX6000AAA61 | 94.95 | 96.17 | +1.22 | +1.29% |
| IG | 14 | NWG | NatWest Group PLC | UK | 7.3% | 98.07 | 312bp | 7.62% | 2034-11-19 | 2.94% | BBB-/Baa3/BBB- | US639057AT53 | 96.83 | 98.07 | +1.24 | +1.28% |
| IG | 15 | LLOYDS | Lloyds banks | UK | 6.75% | 98.61 | 245bp | 7.08% | 2031-09-26 | 3.15% | BBB-/Baa3/BBB | US53944YBB83 | 97.38 | 98.61 | +1.23 | +1.26% |
IG/HY leftmost (same rule as main table). Δ = latest − prior (pts) · ~5d % = Δ / prior · ranked by |%|. Indicative only — not investment advice.
Top 10 widest Z-S · Call ≥ 18 months from as-of 2026-10-30 (cutoff 2028-04-30): 80 eligible (of 95 with Z-S). Ignores on-page YTC < 7% / search filters. −5D rank vs 2026-10-23 (7d earlier).
| IG/HY | # | BBG ticker | Name | Country | Cpn | PX | Z-S | YTC | Call | −5D |
|---|---|---|---|---|---|---|---|---|---|---|
| HY | 1 | SOCGEN | Societe Generale SA | France | 10% | 104.33 | 477bp | 8.05% | 2028-12-13 | 2 |
| HY | 2 | SOCGEN | Societe Generale SA | France | 8.125% | 99.60 | 467bp | 8.26% | 2029-11-20 | 1 |
| IG | 3 | INTNED | ING Groep NV | Netherlands | 7.5% | 100.96 | 446bp | 6.97% | 2028-05-15 | 3 |
| IG | 4 | BNP | BNP Paribas SA | France | 7.125% | 93.02 | 424bp | 8.75% | 2032-02-16 | 5 |
| HY | 5 | SOCGEN | Societe Generale SA | France | 7.125% | 89.95 | 408bp | 8.76% | 2035-07-14 | 9 |
| HY | 6 | SOCGEN | Societe Generale SA | France | 8% | 95.88 | 408bp | 8.85% | 2033-03-29 | 6 |
| IG | 7 | BNP | BNP Paribas SA | France | 6.875% | 90.99 | 406bp | 8.53% | 2033-12-14 | 10 |
| HY | 8 | SOCGEN | Societe Generale SA | France | 5.375% | 90.57 | 400bp | 7.91% | 2030-11-17 | 7 |
| IG | 9 | UBS | UBS Group AG | Switzerland | 9.25% | 104.99 | 396bp | 7.04% | 2028-11-12 | 13 |
| IG | 10 | BNP | BNP Paribas SA | France | 4.5% | 89.02 | 383bp | 8.17% | 2030-02-24 | 8 |
IG/HY leftmost. Widest flat Z-spread vs US Treasury CMT zeros (bp). Excludes Call < 18 months to as-of. Indicative only.
Lowest 10 tightest Z-S · Call ≥ 12 months from as-of 2026-10-30 (cutoff 2027-10-30): 88 eligible (of 95 with Z-S). Ignores on-page YTC < 7% / search filters. −5D rank vs 2026-10-23 (7d earlier).
| IG/HY | # | BBG ticker | Name | Country | Cpn | PX | Z-S | YTC | Call | −5D |
|---|---|---|---|---|---|---|---|---|---|---|
| IG | 1 | LLOYDS | Lloyds banks | UK | 8% | 103.11 | 235bp | 6.84% | 2029-09-26 | 5 |
| IG | 2 | MUFG | MUFG Group | Japan | 8.2% | 104.54 | 238bp | 6.21% | 2029-01-14 | 1 |
| IG | 3 | HSBC | HSBC Holdings PLC | UK | 6.875% | 99.96 | 240bp | 6.89% | 2030-09-10 | 2 |
| IG | 4 | LLOYDS | Lloyds banks | UK | 6.75% | 98.61 | 245bp | 7.08% | 2031-09-26 | 9 |
| IG | 5 | HSBC | HSBC Holdings PLC | UK | 6.95% | 98.35 | 246bp | 7.23% | 2034-09-10 | 6 |
| IG | 6 | MUFG | MUFG Group | Japan | 6.35% | 94.26 | 248bp | 7.19% | 2036-01-14 | 4 |
| IG | 7 | HSBC | HSBC Holdings PLC | UK | 6.5% | 99.97 | 249bp | 6.52% | 2028-03-22 | 12 |
| IG | 8 | BACR | Barclays PLC | UK | 8% | 102.67 | 252bp | 6.83% | 2029-03-14 | 14 |
| IG | 9 | NDAFH | Nordea Bank Abp | Finland | 6.3% | 96.47 | 253bp | 7.15% | 2031-09-24 | 10 |
| IG | 10 | UBS | UBS Group AG | Switzerland | 7.75% | 102.08 | 253bp | 7.20% | 2031-04-12 | 7 |
IG/HY leftmost. Tightest flat Z-spread vs US Treasury CMT zeros (bp). Excludes Call < 12 months to as-of. Indicative only.
Most-clicked / important / high-impact stories for bank names in this universe (keywords like HSBC, UBS, BNP, … — not necessarily the bond itself). Sources: FT, Bloomberg, Reuters, WSJ, Nikkei Asia, S&P Global Ratings, Moody’s. Cap 10 items.
- UBS CEO Signals Possible Switzerland Exit Over Capital Demands · WSJ · 2026-10-28
- HSBC to open Hong Kong AI Institute following Singapore launch · Reuters · 2026-11-02
- UBS lifts profit to $2.7 billion, speeds up buybacks despite capital concerns · FT/BBG/Reuters · 2026-10-28
- French protests show BNP Paribas what’s in a name · FT · 2026-10-31
- PJT Hires Former UBS Senior Investment Banker L’Esperance · Bloomberg · 2026-10-30
- Mizuho's US track record pays off with role in Anthropic IPO · Nikkei · 2026-10-28
- Hyperscaler valuations look attractive after the recent AI unwind, according to Gerry Fowler at UBS · X · 2026-11-02
- Banco Santander and BBVA are stepping up their efforts to win corporate and investment banking business in the US · X · 2026-10-30
- MUFG taps AI for back-office work as Japan banks bolster India IT teams · Nikkei · 2026-10-22
- Research Update: Standard Chartered Bank (Hong Ko | S&P Global Ratings · S&P · 2026-10-23
Multi-source (FT / Bloomberg / Reuters / WSJ / Nikkei / S&P / Moody’s) · last 14 days · deduped · impact/importance/clicks-proxy + round-robin · bank keywords in this AT1 universe · max 10 · agency sites prefer rating actions / outlook / CreditWatch · X secondary fill only (high-follower / high-engagement; ≤2; prefer press on same event).
Ask Gemini opens Google AI Mode (Gemini) with your question prefilled — native gemini.google.com has no reliable ?q= deep link. Open Gemini app copies the question and opens the Gemini chat UI for paste. Ticker filter below stays separate.
“Do you think banks would still call AT1 bonds on first call if UST yields remain elevated vs the past 5 years? What are the main factors for an AT1 investor — country of issue, the banks themselves — and how do the latest Basel 3 requirements fit in?”
First-call behaviour is an economic and franchise decision, not a hard Basel obligation. Issuers typically redeem when they can refinance AT1 more cheaply than the reset coupon after call; if UST remains elevated (this screen’s US Treasury 5yr CMT mark ~4.94% as of 19 Oct 2026; curve still well above the 2019–21 zero era), low-coupon / low-reset AT1s can look expensive to replace, raising extension risk. Investors still weigh: (1) issuer franchise and regulator optics — repeated non-calls damage AT1 market access even when economics argue for extension; (2) country / resolution regime — EU BRRD / SRB, UK BoE, and Asia supervisors differ on PONV, MREL/TLAC stacking, and call consent practice; (3) distance to trigger and CET1 headroom (Basel AT1 going-concern trigger floor is typically 5.125% CET1/RWA, plus discretionary PONV); (4) replacement cost and investor base depth in USD AT1. On this public AT1D screen (as of 19 Oct 2026), near-dated low-coupon names still sit among the widest Z-spreads — e.g. BNP 4.625% (USF1067PAB25) ~854 bp, INGA 3.875% (US456837AY94) ~689 bp, GLE 9.375% (USF8500RAC63) ~594 bp — consistent with call / extension and country-risk premia rather than a single UST path. Basel III finalisation (output floor phasing; leverage-ratio G-SIB buffer; US agencies’ March 2026 Endgame re-proposal still pending a final rule as of mid-Oct 2026) mainly affects how much AT1 banks need as going-concern Additional Tier 1 and the relative cost of CET1 vs AT1, not an automatic call mandate.
Preview · themes from recent coverage (not a live Gemini capture)
Themes: BIS/BCBS Basel III finalisation & AT1 eligibility (perpetual, discretionary coupons, PONV + going-concern trigger); Fed/FDIC/OCC 19 Mar 2026 capital re-proposals; EBA/SRB BRRD & MREL; FSB TLAC; Bloomberg/FT/Reuters AT1 call & French-bank coverage. Z-spreads and FRED DGS5 from this screen (as of 19 Oct 2026).
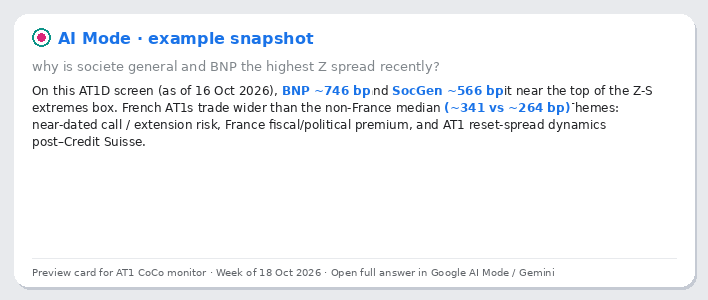
“why is societe general and BNP the highest Z spread recently?”
On this AT1D screen (as of 16 Oct 2026), Société Générale (GLE) and BNP Paribas sit among the widest Z-spreads in the developed-market USD AT1 book: BNP’s 4.625% AT1 (USF1067PAB25) ~746 bp and SocGen’s 9.375% AT1 (USF8500RAC63) ~566 bp rank near the top of the Z-S extremes box. French AT1s as a group also trade wider than the non-France median (~341 bp vs ~264 bp). Shared drivers in recent coverage: near-dated call / extension risk on lower-coupon AT1s, a France fiscal/political risk premium for domestic banks, and AT1 reset-spread dynamics in the post–Credit Suisse CoCo regime.
Preview · themes from recent coverage (not a live Gemini capture)
Themes drawn from Bloomberg / Reuters French-bank & AT1 coverage, ECB / ACPR capital commentary, and this screen’s Z-spread marks (US Treasury CMT curve · as of 16 Oct 2026).
- CET1 / going-concern stack. Common Equity Tier 1 is the core of risk-based capital (minimum 4.5% CET1 + capital conservation buffer 2.5% = 7% CET1 floor before G-SIB / countercyclical add-ons). AT1 sits above CET1 in the going-concern stack but below CET1 in loss absorbency. BIS Basel III
- AT1 as Additional Tier 1 (CoCo design). To qualify as AT1: perpetual; discretionary non-cumulative coupons; write-down or conversion at a going-concern trigger (Basel floor typically 5.125% CET1/RWA) plus a discretionary point of non-viability (PONV) trigger. Coupons can be cancelled without default. BCBS d424 summary
- Leverage ratio. Non-risk-based Tier 1 leverage backstop (Basel minimum 3% of exposure measure) plus a G-SIB leverage buffer equal to 50% of the risk-weighted G-SIB surcharge — met with Tier 1 (CET1 + AT1). BCBS finalisation
- Output floor / Basel III finalisation. Floored RWA = max(model RWA, phased % of standardised RWA). International phase-in: 70% in 2026 → 72.5% in 2027. US agencies re-proposed Endgame / capital modernisation on 19 Mar 2026; comments closed mid-2026 — final rule still pending as of mid-Oct 2026 (Fed expects year-end). Fed 19 Mar 2026 · BIS output floor
- TLAC / MREL interaction. G-SIB TLAC (FSB) and EU/UK MREL sit alongside Pillar 1 capital. AT1 can count toward some loss-absorbing capacity metrics but is primarily going-concern capital; gone-concern resolution layers are usually senior / Tier 2. Jurisdiction (EU BRRD/SRB, UK BoE, Asia) shapes bail-in order and call practice. FSB TLAC · SRB MREL
Public AT1D universe only (no private sleeve). Ranked by Z-S desc among names with >18 months to call (near-call Z jumps excluded; missing call date excluded). Columns: BBG ticker · coupon% perp · Country · Price (Invesco ETF mark) · Z-S · Call · ISIN · Prospectus (SEC/Bondblox URL when stored; otherwise public ISIN search — no invented hosts). Call date from enrichment / holdings when available.
| BBG ticker · coupon | Country | Price | Z-S (bp) | Call | ISIN | Prospectus |
|---|---|---|---|---|---|---|
| SOCGEN 10% perp | France | 104.33 | 477 | 2028-12-13 | USF8600KAA46 | Search |
| SOCGEN 8.125% perp | France | 99.60 | 467 | 2029-11-20 | USF8500RAE20 | Search |
| INTNED 7.5% perp | Netherlands | 100.96 | 446 | 2028-05-15 | XS2585240984 | Search |
| BNP 7.125% perp | France | 93.02 | 424 | 2032-02-16 | USF1067PAL07 | Search |
| SOCGEN 7.125% perp | France | 89.95 | 408 | 2035-07-14 | USF8500RAF94 | Search |
| SOCGEN 8% perp | France | 95.88 | 408 | 2033-03-29 | USF8500EAA94 | Bondblox |
| BNP 6.875% perp | France | 90.99 | 406 | 2033-12-14 | USF1067PAJ50 | Search |
| SOCGEN 5.375% perp | France | 90.57 | 400 | 2030-11-17 | USF8500RAA08 | Search |
Core AT1 CoCo requirement (Basel): perpetual Additional Tier 1 with discretionary coupons; going-concern trigger ≥ 5.125% CET1/RWA (jurisdiction may set higher, e.g. 7%); plus supervisory PONV write-down/conversion. Prospectus column links a stored SEC FWP/424B or Bondblox URL when we have one; otherwise a public search for that ISIN.